Table of Contents
Budgeting often sounds simple until you actually have to decide what to cut.
Housing is clearly important. Groceries matter. Transportation may be necessary for work.
But what about a more expensive phone plan? Restaurant meals? A gym membership? Streaming subscriptions? A car that costs more than you technically need?
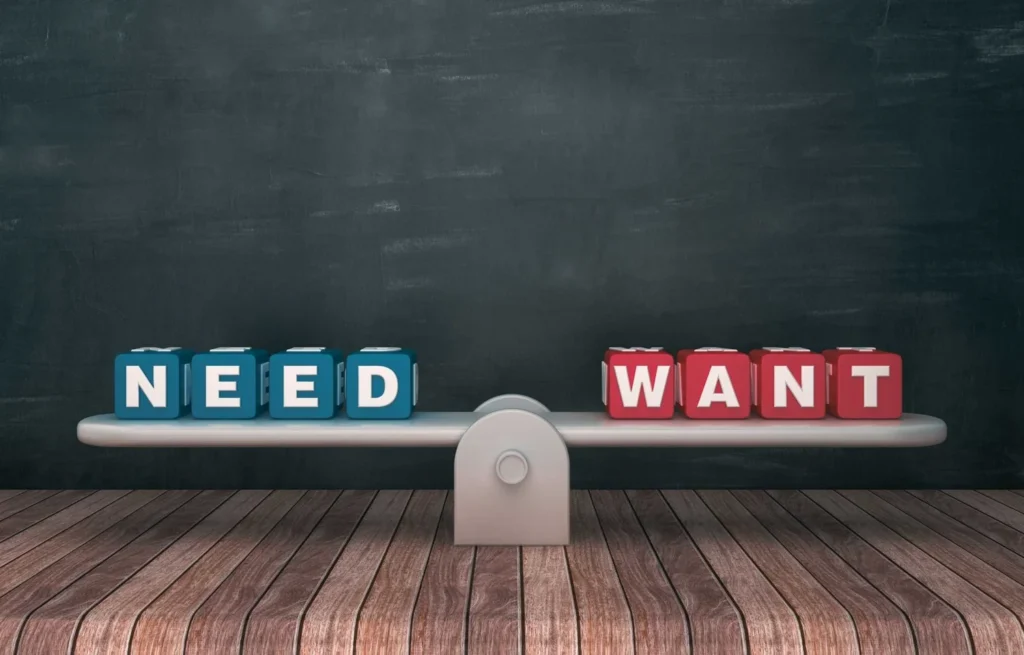
That is why understanding needs vs wants is more useful than simply labeling every expense as “good” or “bad.”
A need is generally something necessary for basic living, work, health, or important financial obligations. A want improves comfort, convenience, entertainment, or lifestyle but can usually be reduced, postponed, or replaced with a less expensive option.
The difficult part is that real life rarely fits perfectly into those definitions.
Why Needs vs Wants Is Not Always Obvious
Consider transportation.
For someone who works from home and lives close to public transportation, owning a car might be optional.
For someone who works night shifts in an area without reliable public transit, transportation may be essential.
Even then, the car itself can contain both a need and a want.
Reliable transportation may be necessary. A brand-new luxury vehicle with an expensive monthly payment may not be.
Food works the same way.
Groceries are clearly part of basic living expenses. Dining at an expensive restaurant every weekend is more likely to fall into the wants category.
The important lesson is that the category depends partly on the purpose of the expense, not simply its name.
How Needs vs Wants Can Improve a Budget
Suppose your take-home income is $5,000 a month and your expenses have gradually climbed to $4,900.
You know something needs to change, but looking at one large total does not tell you where to begin.
Separating needs vs wants can make the picture clearer.
Your rent, basic groceries, insurance, essential transportation, utilities, and minimum required debt payments may be relatively difficult to reduce immediately.
Other expenses may have more flexibility.
Perhaps you are spending $400 on restaurant meals, $150 on multiple subscriptions, and $300 on discretionary shopping.
You do not necessarily have to eliminate all of those things.
Instead, the distinction gives you somewhere to look when your financial priorities change.
If you want to build an emergency fund more quickly, reducing $250 of flexible spending can create savings without pretending your rent or electric bill can disappear.
A Want Is Not Automatically a Waste of Money
This is where many budgeting conversations become unnecessarily negative.
Wanting something does not make it irresponsible.
Entertainment, travel, hobbies, eating out, and convenience can all improve quality of life.
A budget should not simply remove everything enjoyable.
The problem occurs when wants quietly consume money that you intended to use for something more important.
Imagine someone says building an emergency fund is their top priority but spends $600 each month on optional purchases without realizing it.
The issue is not that those purchases are morally wrong.
The issue is that the spending does not match the person’s stated priority.
Understanding needs and wants makes those tradeoffs visible.
Some Expenses Can Move Between the Two Categories
A smartphone provides a good example.
For many people, having a phone is effectively necessary for work, communication, banking, authentication, and emergencies.
But that does not mean every part of the phone expense is essential.
A basic reliable device may meet the need. Upgrading every year to the most expensive model may be a want.
Internet service can be similar.
Reliable internet may be necessary for someone working remotely. Paying extra for a premium package far beyond what the household uses may be optional.
This is why rigid categories are less helpful than asking a better question:
What part of this expense is necessary, and what part is optional?
How This Fits With the 50/30/20 Budget Rule
Your 50/30/20 Budget Rule article already uses a similar idea.
That framework generally separates income into needs, wants, and financial priorities such as saving or debt repayment.
Understanding the difference between needs and wants can make that framework easier to use.
It can also work alongside zero-based budgeting.
When assigning your monthly income, you can cover essential commitments first, assign money toward financial goals, and then deliberately decide how much remains available for lifestyle spending.
The point is not to follow one percentage perfectly.
The point is to make spending intentional.
Consumer.gov’s budgeting guidance also emphasizes planning how money will be used and reviewing actual spending so the next month’s budget can be adjusted.
Final Takeaway
The difference between needs vs wants is not about deciding which expenses are good people allowed to have.
It is about understanding priorities.
Needs usually protect basic living, work, health, and important obligations. Wants provide comfort, convenience, enjoyment, or upgrades beyond what is necessary.
Some expenses contain a little of both.
When money becomes tight or you want to save more, this distinction gives you a practical place to start.
You do not have to eliminate everything you enjoy.
You simply need to know which expenses you can change when something else becomes more important.
Financial disclaimer: This article is for general educational purposes and is not personalized financial advice.